
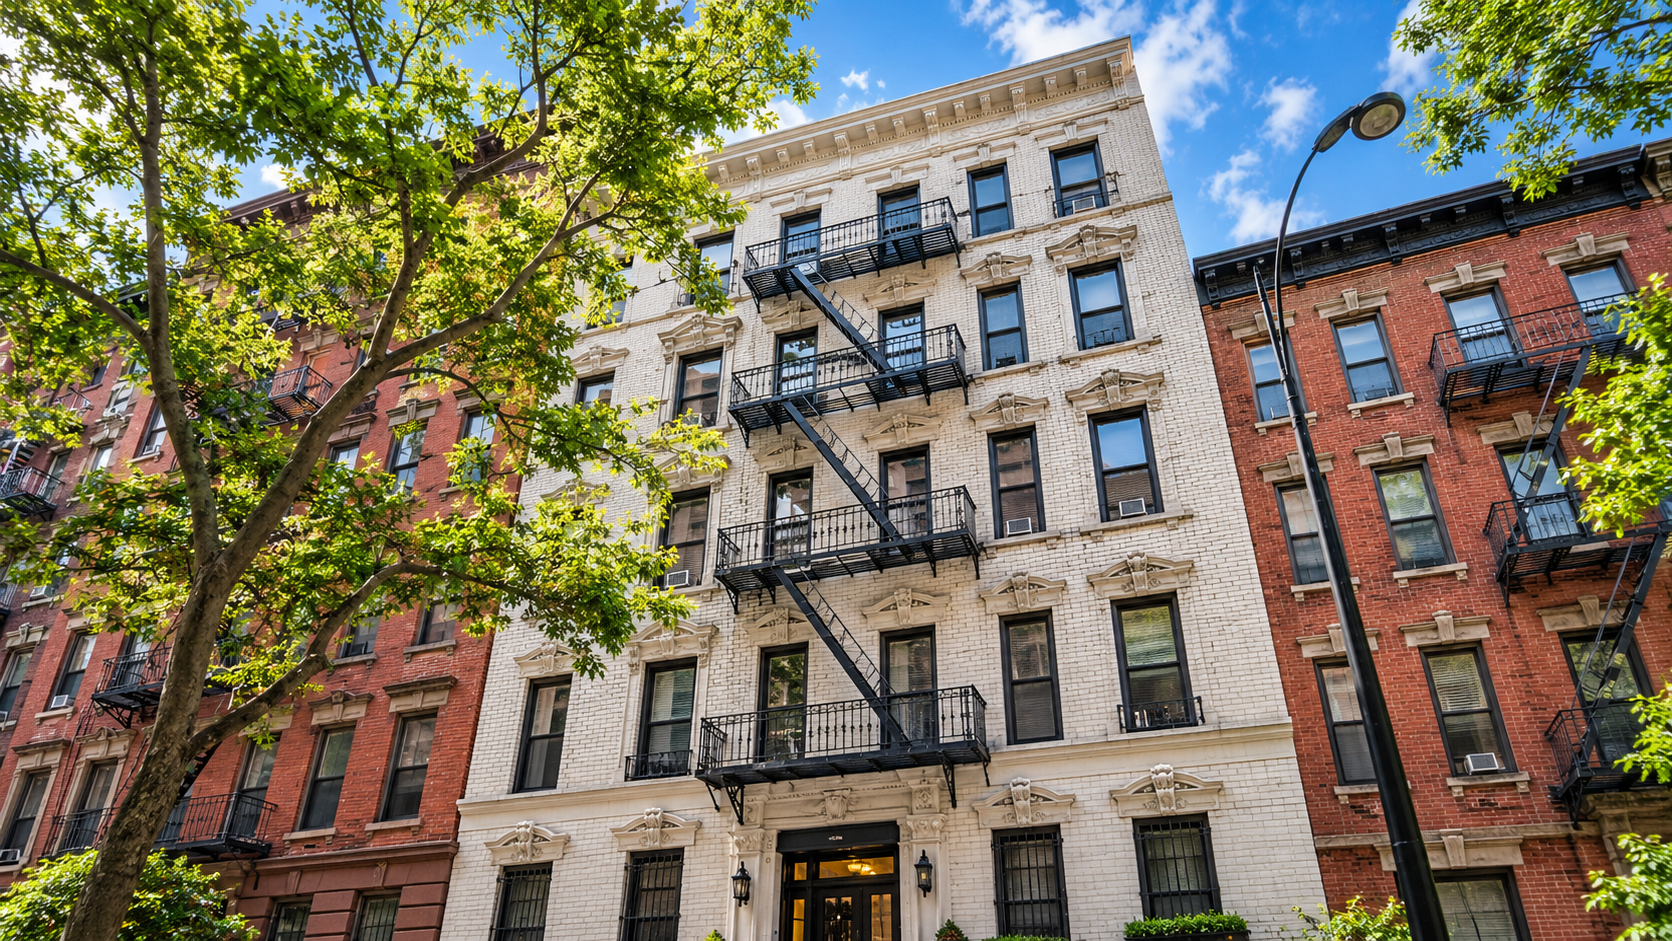
Affordable Housing Property Tax Appeals & Portfolio Reviews
Affordable housing cannot always be valued like unrestricted multifamily property.
Lovett Property Tax Advisors works with owners, developers, asset managers and property managers of LIHTC, HUD, USDA/RD, HOME, Section 8, PBRA and other rent-restricted properties to evaluate assessments based on the property's actual economics, regulatory restrictions and subsidy structure.
Our affordable housing property tax appeals, including LIHTC property tax appeals, are grounded in each property's actual restrictions and operating data.
For owners and managers with multiple properties, we can also review an entire portfolio, identify the assets that warrant closer attention, prioritize potential appeal opportunities and help coordinate deadlines across jurisdictions.
WHO WE HELP
Affordable housing owners and developers
LIHTC owners, developers and syndicators
Owners of USDA/Rural Development properties
Multifamily portfolio owners
Nonprofit and mission-driven housing organizations
Owners of HOME-funded properties
Asset managers
Public housing authority-affiliated owners
Owners of Section 8 and PBRA properties
Affordable housing property management companies
Owners of HUD-insured and HUD-assisted properties
Investors and acquisition teams evaluating future property tax exposure
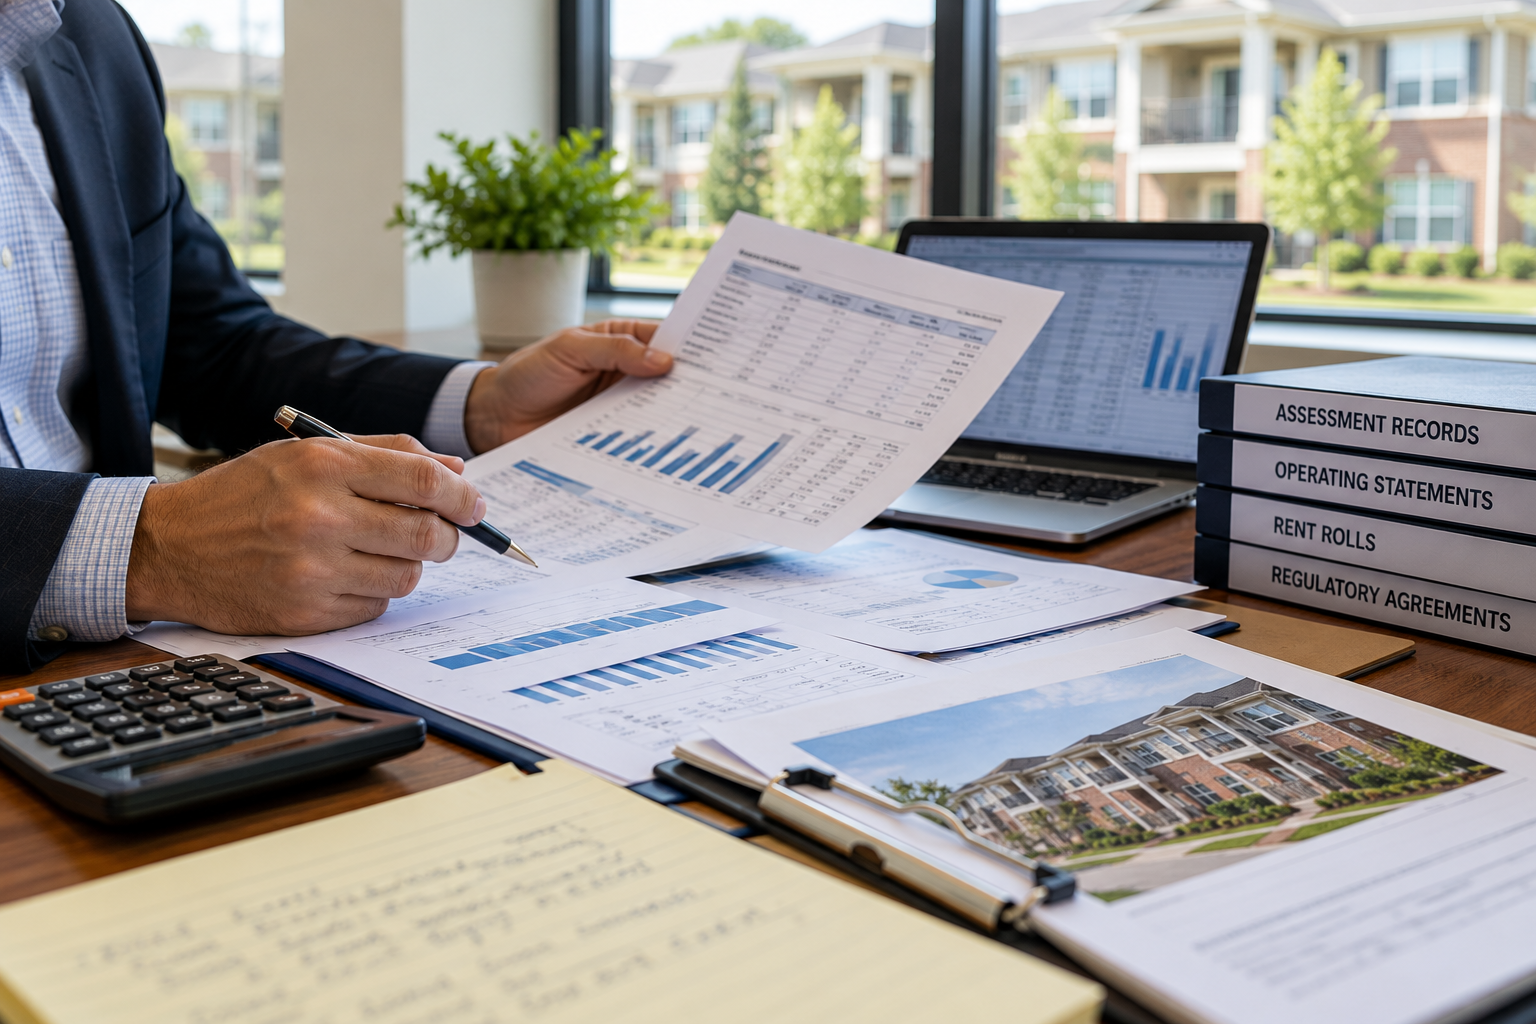
AFFORDABLE HOUSING PORTFOLIO ASSESSMENT REVIEW
For organizations that own or manage multiple affordable housing properties, property tax strategy should not begin only when an appeal deadline arrives.
LovettPTA can review a portfolio to help determine where attention is warranted before resources are committed to individual appeals.
Each affordable housing property tax assessment in the portfolio is measured against the property's actual restrictions and operating performance.
Reviewing current and prior assessed values
Identifying unusually large year-over-year assessment increases
Comparing assessments with actual property operating performance
Reviewing rent restrictions and regulatory structures
Identifying properties where restricted economics may not be adequately reflected in the assessment
Evaluating prior appeal history
Prioritizing properties presenting the strongest potential opportunities
Tracking appeal deadlines across counties and states
Providing consolidated recommendations to ownership or management
The objective is not to appeal every property. It is to help the owner or manager focus time and resources on the properties where further review is justified.
Affordable housing properties operate under economic and regulatory constraints that may differ substantially from unrestricted market-rate apartments.
An assessment may warrant closer review when valuation assumptions do not adequately account for those differences.
WHY AFFORDABLE HOUSING IS FREQUENTLY MISVALUED
Common issues:
01
Use of market rents rather than restricted or contract rents
02
Reliance on unrestricted multifamily sales without appropriate adjustments
03
Failure to consider income or rent restrictions
04
Insufficient consideration of regulatory agreements
05
Use of income or expense assumptions inconsistent with actual operations
06
Failure to recognize additional compliance, reporting or management costs
07
Inappropriate treatment of subsidies, financing structures or tax-credit-related value
08
Assessment increases following a sale or refinancing even though the property's earning capacity remains restricted
When these issues are present, rent-restricted property tax appeals may be appropriate.
The proper treatment of these issues varies by jurisdiction and by the particular affordable housing program. Our analysis therefore begins with the property's actual structure and the law governing the assessment.
AFFORDABLE HOUSING PROGRAMS WE REVIEW
LIHTC PROPERTY TAX VALUATION
Low-Income Housing Tax Credit properties are subject to rent limits, income restrictions, compliance requirements and extended-use obligations that can materially affect the property's operating economics.
We review the actual restricted rents, unit mix, operating results, applicable land-use or extended-use agreements and other relevant restrictions when evaluating whether an assessment reasonably reflects the property.
Depending on the jurisdiction and circumstances, questions may also arise concerning the treatment of tax-credit-related benefits, financing structures and sales involving LIHTC properties. Where the assessment does not reasonably reflect these restrictions, LIHTC property tax appeals may be warranted.
HUD AND HUD-ASSISTED PROPERTIES
HUD properties may be subject to regulatory agreements, rent limitations, HAP contracts, distribution restrictions and other requirements that distinguish them from unrestricted multifamily properties.
Our review focuses on the property's actual income stream, regulatory framework, operating costs and the valuation methodology used by the assessing authority.
USDA / RURAL DEVELOPMENT PROPERTIES
USDA/RD properties, including Section 515 and Section 538 housing, may involve restricted rents, rental assistance, below-market financing, interest-credit arrangements and substantial operating requirements.
Those features should be understood before treating an RD property as economically equivalent to an unrestricted apartment complex.
LovettPTA reviews the applicable RD structure along with actual operating performance when evaluating the assessment.
SECTION 8 AND PBRA PROPERTIES
Section 8 and Project-Based Rental Assistance properties may have contract rents and subsidy structures that differ materially from prevailing unrestricted market rents.
We review the HAP or PBRA structure, contract rents, property operating history and applicable restrictions when analyzing the assessment.
HOME AND OTHER RENT-RESTRICTED HOUSING
HOME-funded properties and developments participating in state, local, bond-financed or other affordability programs may also be subject to rent, income and use restrictions.
Our review focuses on how those restrictions affect the property's actual economics and whether the assessment adequately reflects them.
WHAT WE REVIEW
Regulatory and Program Documents
Land Use Restriction Agreements
Extended Use Agreements
Regulatory agreements
HAP and PBRA contracts
USDA/RD loan and rental-assistance documents
HOME restrictions
Other affordability agreements
Relevant subsidy and financing documents
Property Operations
Current rent roll
Unit-level restrictions
Actual income and expense statements
Operating budgets
Audited financial statements
Vacancy and collection history
Compliance and management expenses
Agency or compliance reports
Assessment and Tax Information
Current and prior assessment notices
Property record cards
Assessor valuation workpapers when available
Prior appeal history
Property tax bills
Comparable assessments where relevant
Transaction Information
Purchase information
Refinancing documents
Appraisals where available
Relevant financing structure
COMMON ISSUES THAT MAY SUPPORT FURTHER REVIEW
Market rents are used instead of restricted or contract rents
Actual income and expenses are disregarded
Expense assumptions are materially below actual operating experience
Compliance and management costs are understated
Regulatory restrictions are not adequately considered
Subsidy or financing-related value may have been improperly reflected in taxable real-property value
The assessment increases sharply after a sale or refinancing
Vacancy or collection loss is understated
The property's classification, unit count or square footage is incorrect
Similar restricted properties receive inconsistent assessment treatment
The increase in assessed value appears disconnected from actual operating performance
Not every issue produces an appeal. Our role is to determine whether the circumstances justify further analysis and, where appropriate, challenge the assessment.
OUR PROCESS
1. Initial Assessment or Portfolio Review
We review the assessment, property structure, restrictions and available financial information to determine whether further analysis is warranted.
2. Valuation Analysis
Where appropriate, we evaluate the property's actual income, expenses, regulatory restrictions, subsidy structure and applicable valuation methodology.
3. Recommendation
We review the assessment, property structure, restrictions and available financial information to determine whether further analysis is warranted.
4. Administrative Appeal and Negotiation
Where engaged to proceed, LovettPTA handles the administrative appeal and works with the assessing authority to seek an appropriate resolution. Each low-income housing property tax appeal is supported by the property's restricted income, actual expenses and governing regulatory documents.
5. Further Appeal or Litigation When Appropriate
When the administrative process does not produce a reasonable result, we evaluate available further-appeal and litigation options with the client.
6. Ongoing Portfolio Monitoring
For portfolio clients, we can continue monitoring assessment changes and future appeal opportunities.
WHY CHOOSE LOVETT PROPERTY TAX ADVISORS
$1.2 billion+
in appealed property value
Focused experience with affordable and rent-restricted multifamily properties
Familiarity with LIHTC, HUD, USDA/RD, HOME, Section 8 and PBRA structures
Attorney-led property tax strategy
Property-level and portfolio-level review
Detailed income and expense analysis
Administrative appeal, negotiation and litigation capability
More than $1.2 billion in appealed property value
Direct involvement and individualized recommendations rather than a volume-driven approach
Experience working with affordable housing properties across multiple Southeastern jurisdictions
AFFORDABLE HOUSING PROPERTY TAX SERVICES ACROSS THE SOUTHEAST
Lovett Property Tax Advisors works with property owners and managers across multiple Southeastern jurisdictions to evaluate property tax assessments, analyze valuation issues and support appropriate appeal strategies.
Because property tax laws, valuation standards and appeal procedures vary by state and county, each property is evaluated under the requirements applicable to its jurisdiction. Where legal representation is required, LovettPTA works with appropriate counsel authorized to practice in that jurisdiction.
FAQ
-
Yes. LIHTC properties generally have the same right to challenge assessments as other real property, although the valuation issues and appeal procedures vary by jurisdiction.
-
There is no single rule that applies in each jurisdiction. Relevant considerations may include restricted rents, actual income and expenses, regulatory agreements, affordability restrictions and applicable statutory or case-law requirements.
-
They can. Restrictions that limit the income a property can legally generate may be relevant to valuation, although their treatment depends on applicable state law and assessment methodology.
-
Yes. LovettPTA works with HUD-assisted, USDA/RD and other subsidized or rent-restricted multifamily properties and evaluates the particular regulatory, rental-assistance and financing structure involved.
-
Yes. Owners and managers can submit multiple properties for review. We can help identify which properties merit additional analysis, prioritize potential appeal opportunities and coordinate deadlines across jurisdictions.
-
No. A central purpose of a portfolio review is to distinguish properties that warrant further attention from those where an appeal may not be economically justified.
-
A useful starting package generally includes the current assessment, prior assessed value, recent income and expense information, current rent roll and information concerning applicable rent or regulatory restrictions.
-
Deadlines vary by jurisdiction and may be short. Owners should seek review promptly after receiving an assessment notice.
-
Depending on the jurisdiction and circumstances, additional administrative or judicial appeal rights may be available. LovettPTA evaluates those options with the client.
HAVE AN AFFORDABLE HOUSING PORTFOLIO YOU WOULD LIKE REVIEWED?
Lovett Property Tax Advisors works with property owners and managers across multiple Southeastern jurisdictions to evaluate property tax assessments, analyze valuation issues and support appropriate appeal strategies.
If you manage multiple properties, send us a portfolio schedule and we can begin by identifying the assets that warrant closer review.