
Affordable Housing Property Tax Appeals & Portfolio Reviews
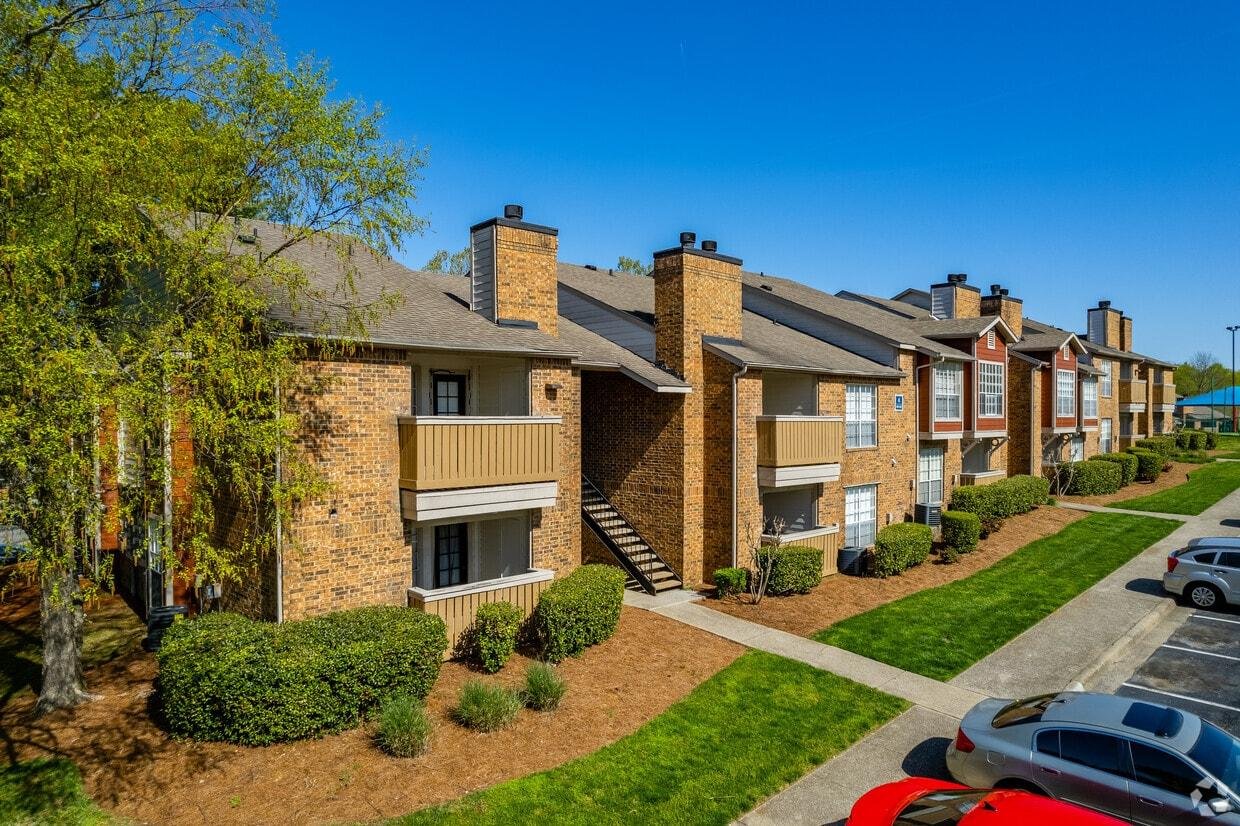
Affordable housing cannot always be valued like unrestricted multifamily property.
Lovett Property Tax Advisors works with owners, developers, asset managers and property managers of LIHTC, HUD, USDA/RD, HOME, Section 8, PBRA and other rent-restricted properties to evaluate assessments based on the property's actual economics, regulatory restrictions and subsidy structure.
Our affordable housing property tax appeals, including LIHTC property tax appeals, are grounded in each property's actual restrictions and operating data.
For owners and managers with multiple properties, we can also review an entire portfolio, identify the assets that warrant closer attention, prioritize potential appeal opportunities and help coordinate deadlines across jurisdictions.
WHO WE HELP
Affordable housing owners and developers
LIHTC owners, developers and syndicators
Owners of USDA/Rural Development properties
Multifamily portfolio owners
Nonprofit and mission-driven housing organizations
Owners of HOME-funded properties
Asset managers
Public housing authority-affiliated owners
Owners of Section 8 and PBRA properties
Affordable housing property management companies
Owners of HUD-insured and HUD-assisted properties
Investors and acquisition teams evaluating future property tax exposure
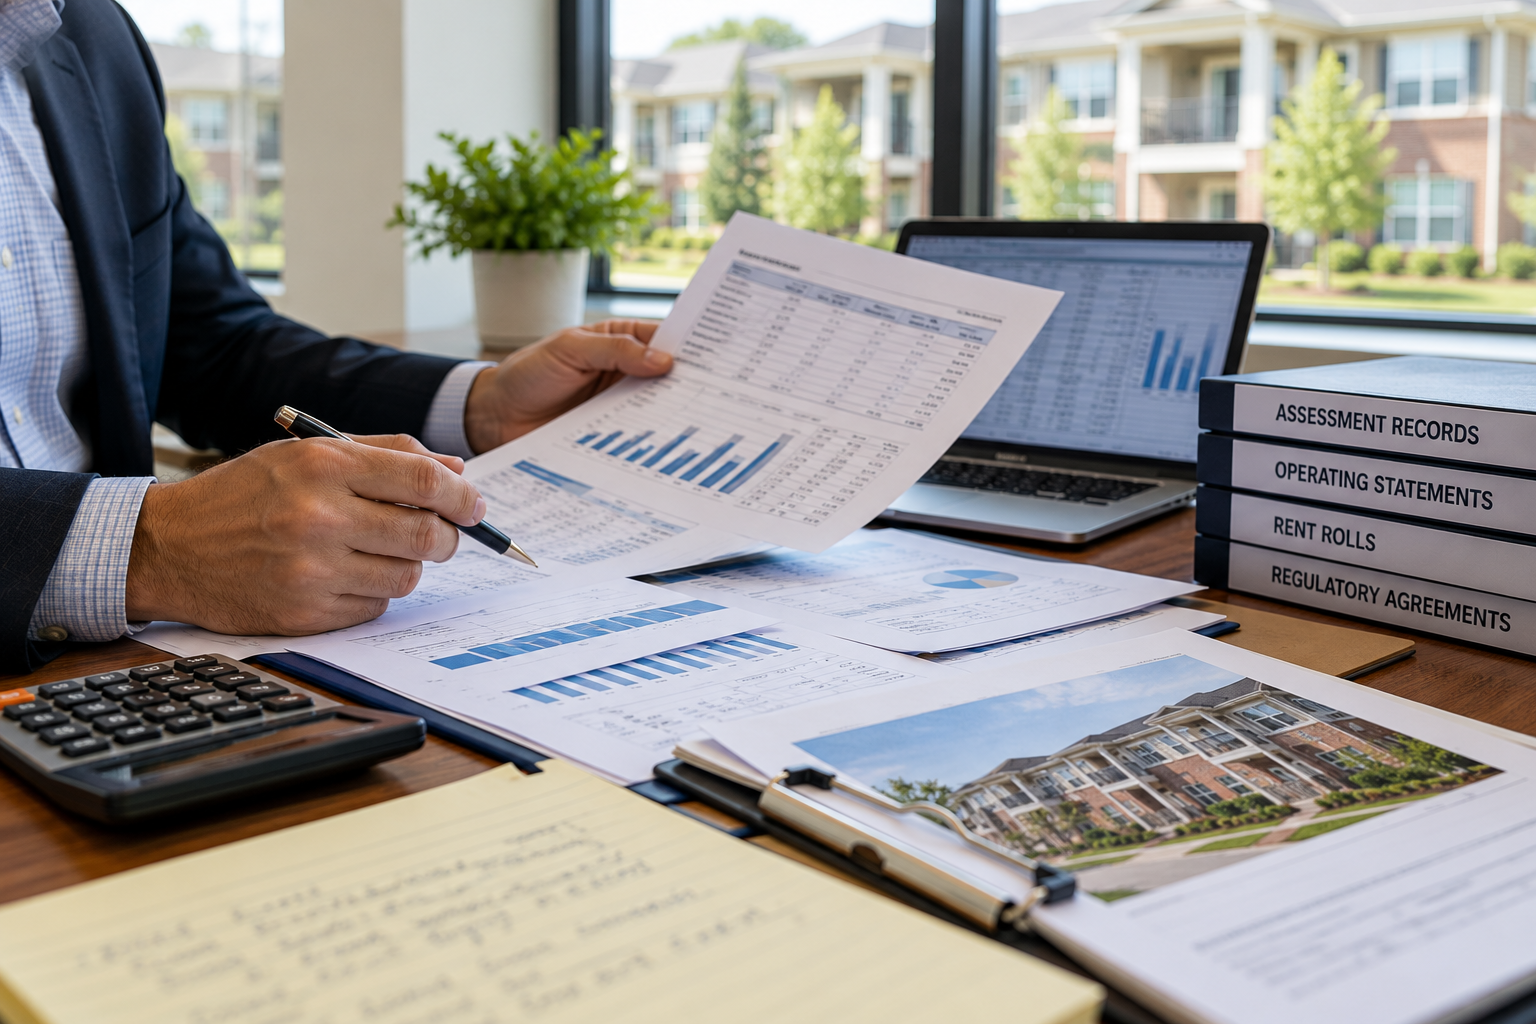
AFFORDABLE HOUSING PORTFOLIO ASSESSMENT REVIEW
For organizations that own or manage multiple affordable housing properties, property tax strategy should not begin only when an appeal deadline arrives.
LovettPTA can review a portfolio to help determine where attention is warranted before resources are committed to individual appeals.
Each affordable housing property tax assessment in the portfolio is measured against the property's actual restrictions and operating performance.
Reviewing current and prior assessed values
Identifying unusually large year-over-year assessment increases
Comparing assessments with actual property operating performance
Reviewing rent restrictions and regulatory structures
Identifying properties where restricted economics may not be adequately reflected in the assessment
Evaluating prior appeal history
Prioritizing properties presenting the strongest potential opportunities
Tracking appeal deadlines across counties and states
Providing consolidated recommendations to ownership or management
The objective is not to appeal every property. It is to help the owner or manager focus time and resources on the properties where further review is justified.
WHY AFFORDABLE HOUSING IS FREQUENTLY MISVALUED
01
Use of market rents rather than restricted or contract rents
05
Use of income or expense assumptions inconsistent with actual operations
02
Reliance on unrestricted multifamily sales without appropriate adjustments
06
Failure to recognize additional compliance, reporting or management costs
Affordable housing properties operate under economic and regulatory constraints that may differ substantially from unrestricted market-rate apartments.
An assessment may warrant closer review when valuation assumptions do not adequately account for those differences.
03
Failure to consider income or rent restrictions
07
Inappropriate treatment of subsidies, financing structures or tax-credit-related value
04
Insufficient consideration of regulatory agreements
08
Assessment increases following a sale or refinancing even though the property's earning capacity remains restricted
When these issues are present, rent-restricted property tax appeals may be appropriate.
The proper treatment of these issues varies by jurisdiction and by the particular affordable housing program. Our analysis therefore begins with the property's actual structure and the law governing the assessment.