
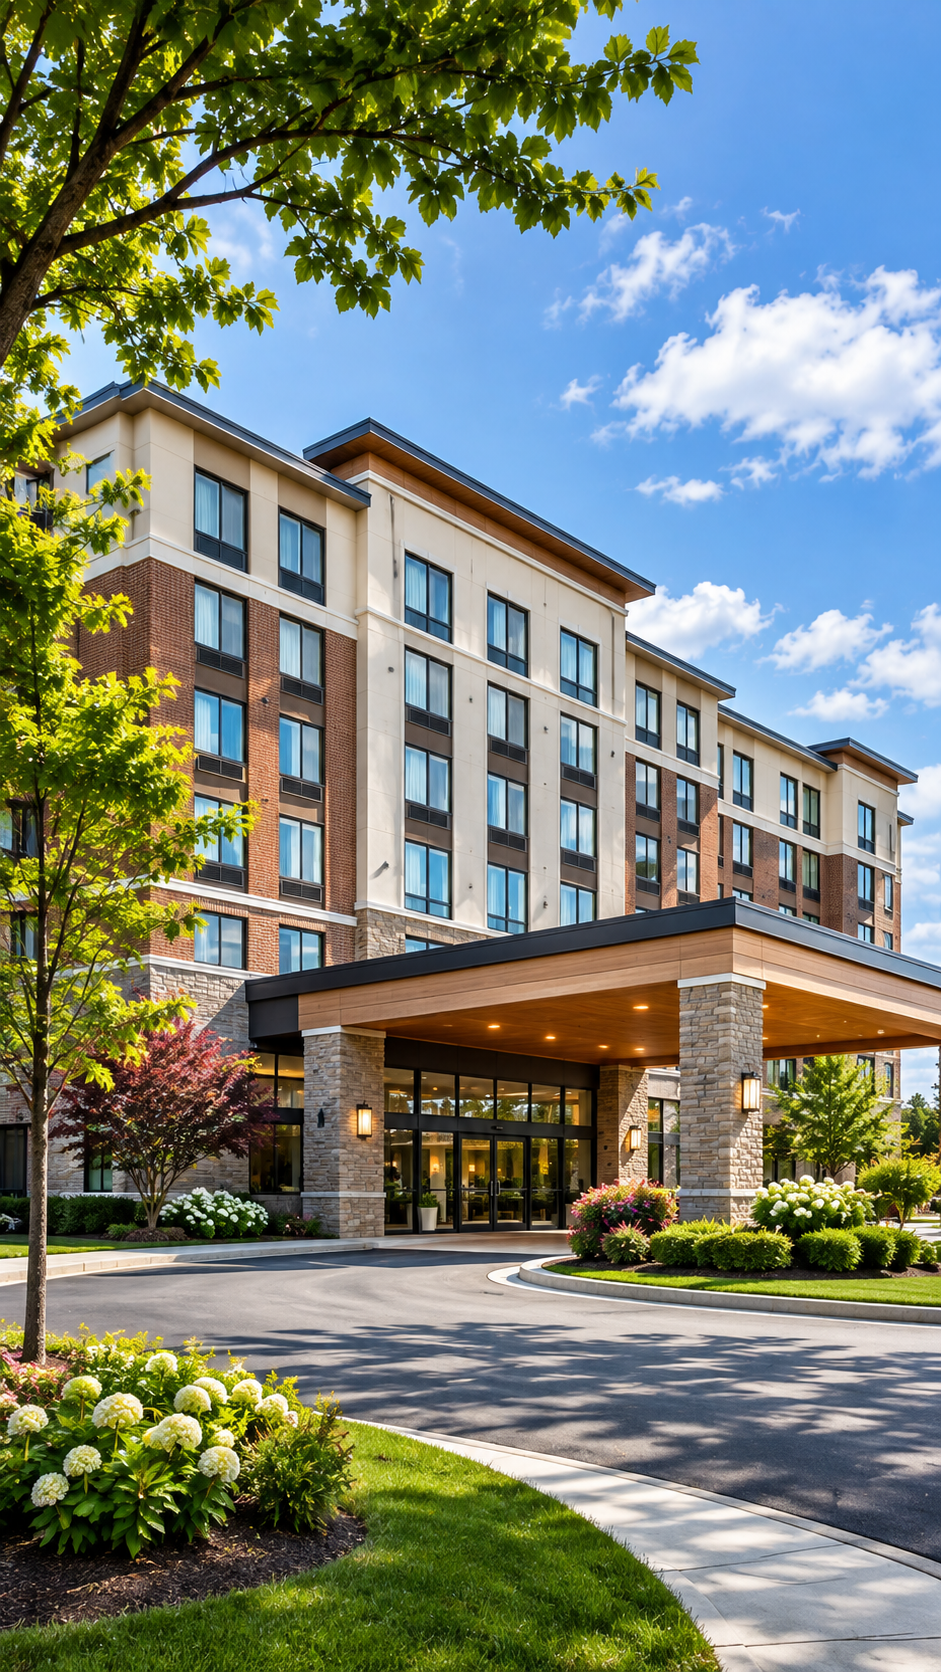
Hotel Property Tax Appeals & Assessment Reviews
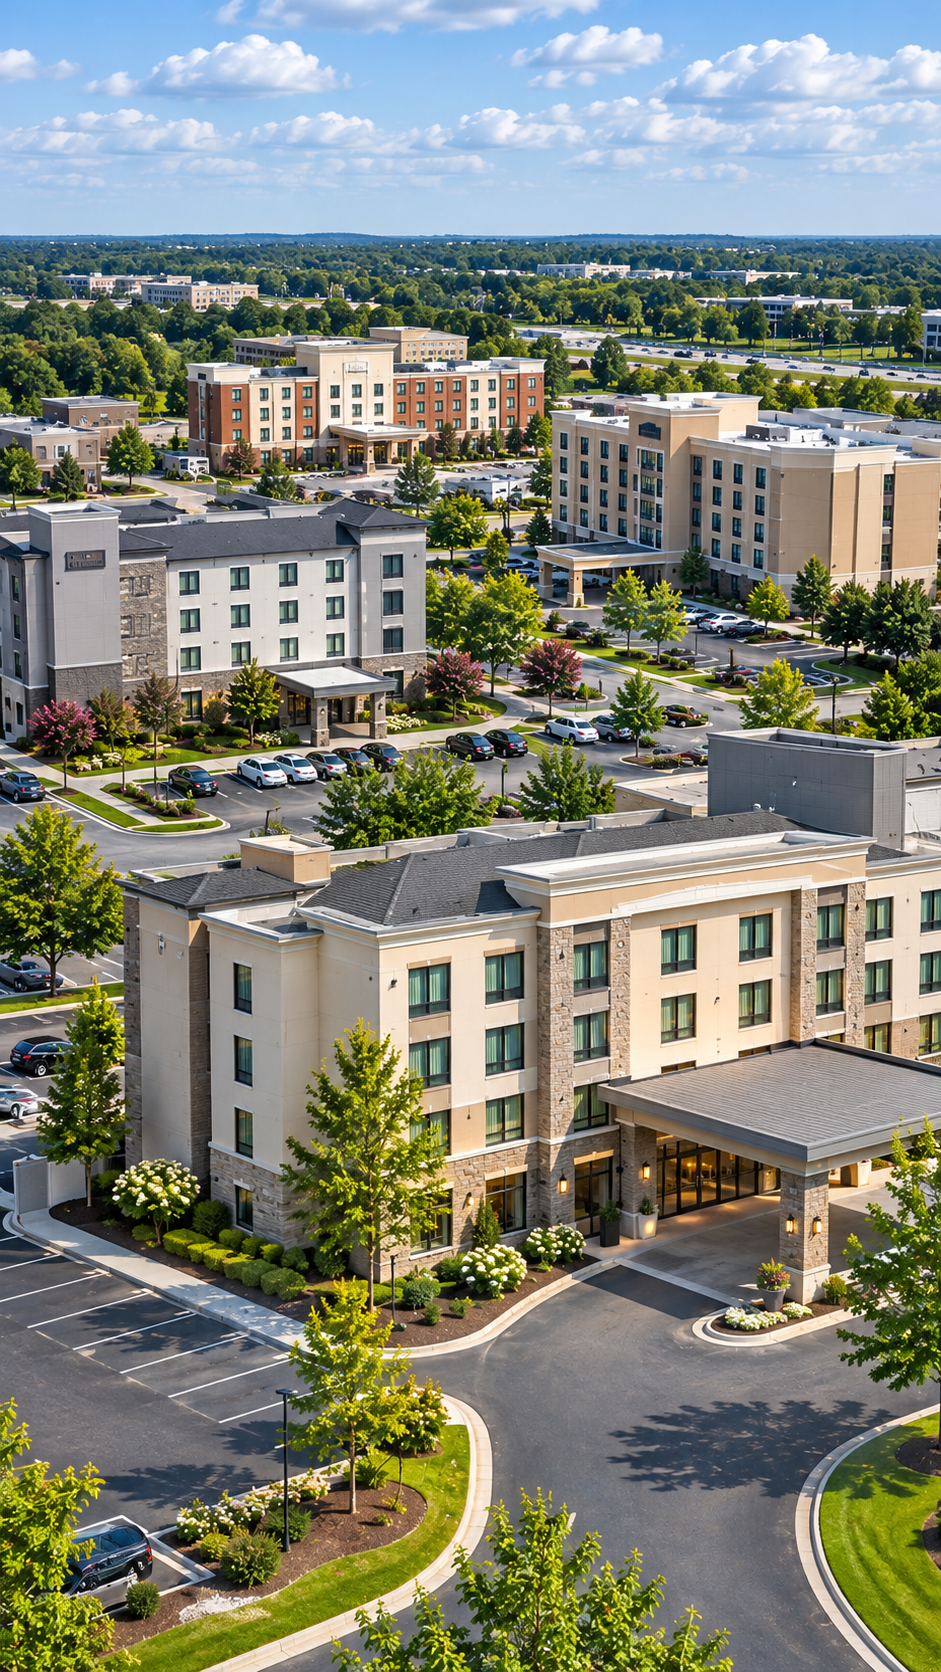
Hotel properties require valuation analysis that reflects their actual operating performance.
Lovett Property Tax Advisors helps hotel owners, investors, developers and property managers evaluate property tax assessments and pursue hotel property tax appeals based on revenue, operating expenses, occupancy, property characteristics and applicable valuation methods.
For owners with multiple hotel properties, LovettPTA can also review an entire portfolio, identify properties that warrant closer attention and prioritize potential appeal opportunities.
WHO WE HELP
Hotel and lodging property owners
Owners experiencing significant assessment increases
Hotel portfolio owners
Property managers
Investors and developers
Asset managers
Owners acquiring or refinancing hotel properties
Hotel management companies
Acquisition teams evaluating future property tax exposure
Hotel Property Tax Portfolio Review
For owners and managers with multiple hotel properties, property tax strategy should not begin only when an appeal deadline arrives.
LovettPTA can review a hotel portfolio to identify properties where assessment assumptions or valuation changes may warrant further analysis.
Current and prior assessed values
Year-over-year assessment changes
Hotel revenue and operating performance
Occupancy and room-rate information
Operating expenses
Prior appeal history
Property characteristics and condition
Comparable hotel information
Acquisition or refinancing information
Appeal deadlines
The goal is not to appeal every property. It is to help owners focus resources on properties where further review is justified.
Hotel properties are income-producing assets, and their operating performance can have an important role in valuation.
A hotel property tax assessment may warrant closer review when valuation assumptions do not accurately reflect the hotel's actual economics or market position.
Why Hotel Properties May Be Over-Assessed
Common issues:
01
Incorrect property information
02
Revenue assumptions that do not reflect actual performance
03
Incorrect occupancy assumptions
04
Inaccurate room-rate assumptions
05
Operating expenses that do not reflect actual operations
06
Incorrect capitalization-rate assumptions
07
Inappropriate comparable hotels
08
Physical condition or deferred maintenance not adequately considered
09
Significant or unexplained assessment increases
10
Assessment increases following a sale or refinancing
11
Changes in hotel operations or market conditions not adequately considered
When these issues are present, rent-restricted property tax appeals may be appropriate.
The proper treatment of these issues varies by jurisdiction and by the particular affordable housing program. Our analysis therefore begins with the property's actual structure and the law governing the assessment.
Hotel Property Types & Programs We Review
Full-Service Hotels
Limited-Service Hotels
Extended-Stay Hotels
Boutique & Independent Hotels
Branded & Franchise Hotels
Resort & Destination Properties
Hotel-Condominium & Mixed-Use Properties
Other Lodging Properties
WHAT WE REVIEW
Regulatory and Program Documents
Land Use Restriction Agreements
Extended Use Agreements
Regulatory agreements
HAP and PBRA contracts
USDA/RD loan and rental-assistance documents
HOME restrictions
Other affordability agreements
Relevant subsidy and financing documents
Property Operations
Current rent roll
Unit-level restrictions
Actual income and expense statements
Operating budgets
Audited financial statements
Vacancy and collection history
Compliance and management expenses
Agency or compliance reports
Assessment and Tax Information
Current and prior assessment notices
Property record cards
Assessor valuation workpapers when available
Prior appeal history
Property tax bills
Comparable assessments where relevant
Transaction Information
Purchase information
Refinancing documents
Appraisals where available
Relevant financing structure
COMMON ISSUES THAT MAY SUPPORT FURTHER REVIEW
Market rents are used instead of restricted or contract rents
Actual income and expenses are disregarded
Expense assumptions are materially below actual operating experience
Compliance and management costs are understated
Regulatory restrictions are not adequately considered
Subsidy or financing-related value may have been improperly reflected in taxable real-property value
The assessment increases sharply after a sale or refinancing
Vacancy or collection loss is understated
The property's classification, unit count or square footage is incorrect
Similar restricted properties receive inconsistent assessment treatment
The increase in assessed value appears disconnected from actual operating performance
Not every issue produces an appeal. Our role is to determine whether the circumstances justify further analysis and, where appropriate, challenge the assessment.
OUR PROCESS
1. Initial Assessment or Portfolio Review
We review the assessment, property structure, restrictions and available financial information to determine whether further analysis is warranted.
2. Valuation Analysis
Where appropriate, we evaluate the property's actual income, expenses, regulatory restrictions, subsidy structure and applicable valuation methodology.
3. Recommendation
We review the assessment, property structure, restrictions and available financial information to determine whether further analysis is warranted.
4. Administrative Appeal and Negotiation
Where engaged to proceed, LovettPTA handles the administrative appeal and works with the assessing authority to seek an appropriate resolution. Each low-income housing property tax appeal is supported by the property's restricted income, actual expenses and governing regulatory documents.
5. Further Appeal or Litigation When Appropriate
When the administrative process does not produce a reasonable result, we evaluate available further-appeal and litigation options with the client.
6. Ongoing Portfolio Monitoring
For portfolio clients, we can continue monitoring assessment changes and future appeal opportunities.
WHY CHOOSE LOVETT PROPERTY TAX ADVISORS
$1.2 billion+
in appealed property value
Focused experience with affordable and rent-restricted multifamily properties
Familiarity with LIHTC, HUD, USDA/RD, HOME, Section 8 and PBRA structures
Attorney-led property tax strategy
Property-level and portfolio-level review
Detailed income and expense analysis
Administrative appeal, negotiation and litigation capability
More than $1.2 billion in appealed property value
Direct involvement and individualized recommendations rather than a volume-driven approach
Experience working with affordable housing properties across multiple Southeastern jurisdictions
AFFORDABLE HOUSING PROPERTY TAX SERVICES ACROSS THE SOUTHEAST
Lovett Property Tax Advisors works with property owners and managers across multiple Southeastern jurisdictions to evaluate property tax assessments, analyze valuation issues and support appropriate appeal strategies.
Because property tax laws, valuation standards and appeal procedures vary by state and county, each property is evaluated under the requirements applicable to its jurisdiction. Where legal representation is required, LovettPTA works with appropriate counsel authorized to practice in that jurisdiction.
FAQ
-
Yes. LIHTC properties generally have the same right to challenge assessments as other real property, although the valuation issues and appeal procedures vary by jurisdiction.
-
There is no single rule that applies in each jurisdiction. Relevant considerations may include restricted rents, actual income and expenses, regulatory agreements, affordability restrictions and applicable statutory or case-law requirements.
-
They can. Restrictions that limit the income a property can legally generate may be relevant to valuation, although their treatment depends on applicable state law and assessment methodology.
-
Yes. LovettPTA works with HUD-assisted, USDA/RD and other subsidized or rent-restricted multifamily properties and evaluates the particular regulatory, rental-assistance and financing structure involved.
-
Yes. Owners and managers can submit multiple properties for review. We can help identify which properties merit additional analysis, prioritize potential appeal opportunities and coordinate deadlines across jurisdictions.
-
No. A central purpose of a portfolio review is to distinguish properties that warrant further attention from those where an appeal may not be economically justified.
-
A useful starting package generally includes the current assessment, prior assessed value, recent income and expense information, current rent roll and information concerning applicable rent or regulatory restrictions.
-
Deadlines vary by jurisdiction and may be short. Owners should seek review promptly after receiving an assessment notice.
-
Depending on the jurisdiction and circumstances, additional administrative or judicial appeal rights may be available. LovettPTA evaluates those options with the client.
HAVE AN AFFORDABLE HOUSING PORTFOLIO YOU WOULD LIKE REVIEWED?
Lovett Property Tax Advisors works with property owners and managers across multiple Southeastern jurisdictions to evaluate property tax assessments, analyze valuation issues and support appropriate appeal strategies.
If you manage multiple properties, send us a portfolio schedule and we can begin by identifying the assets that warrant closer review.